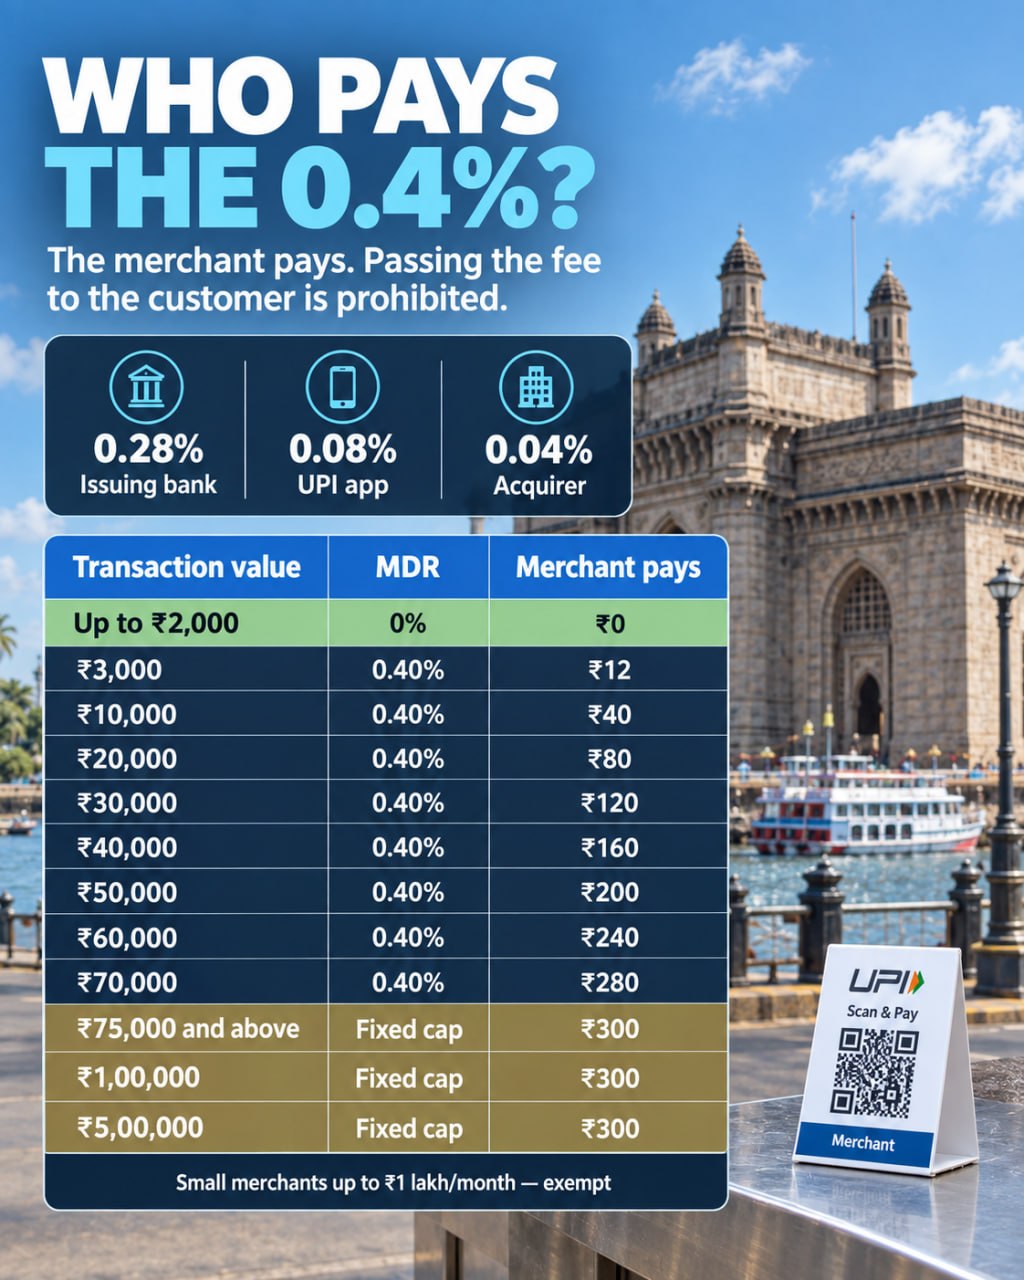
⚡️A key nuance that should not be overlooked: small merchants are exempt. If a merchant accepts payments via QR code under the P2PM scheme for up to ₹1 lakh (₹100,000) per month, no fee applies; exceeding the threshold for three consecutive months moves the merchant into the P2M category.
🛍The merchant pays the fee; the acquiring bank debits it from their account, and passing it on to the customer is prohibited. The 0.4% is distributed as follows: 0.28% to the issuing bank (interchange), 0.08% to the UPI app provider, and 0.04% to the acquirer.
🏦The scale this applies to is far from small: in August, UPI processed 24.5 billion transactions worth approximately ~$340 billion in total. Even 0.4% of a portion of this flow represents a new source of revenue within the system.
Hinglish
🇮🇳UPI P2M MDR ke baare mein thodi aur information add kar raha hoon.💳
⚡️Ek important point jo miss nahi karna chahiye: chhote merchants exempt hote hain. Agar koi point P2PM scheme ke under QR code ke through mahine mein ₹1 lakh (100,000 ₹) tak accept karta hai, to commission nahi lagta. Agar ye limit 3 mahine lagataar cross ho jaye, to merchant P2M category mein chala jata hai.
🛍Commission merchant pay karta hai — acquiring bank uske account se amount deduct karta hai. Iska burden customer par daalna allowed nahi hai. 0.4% ka distribution is tarah hai: 0.28% issuing bank ko (interchange), 0.08% UPI app provider ko, aur 0.04% acquirer ko.
🏦Jis scale par ye apply hota hai, woh chhota nahi hai: August mein UPI ne 24.5 billion transactions process kiye, jinki total value lagbhag $340 billion thi. Is flow ke ek hissa par bhi 0.4% lage, to system ke andar ek naya revenue source ban sakta hai.
 P2P